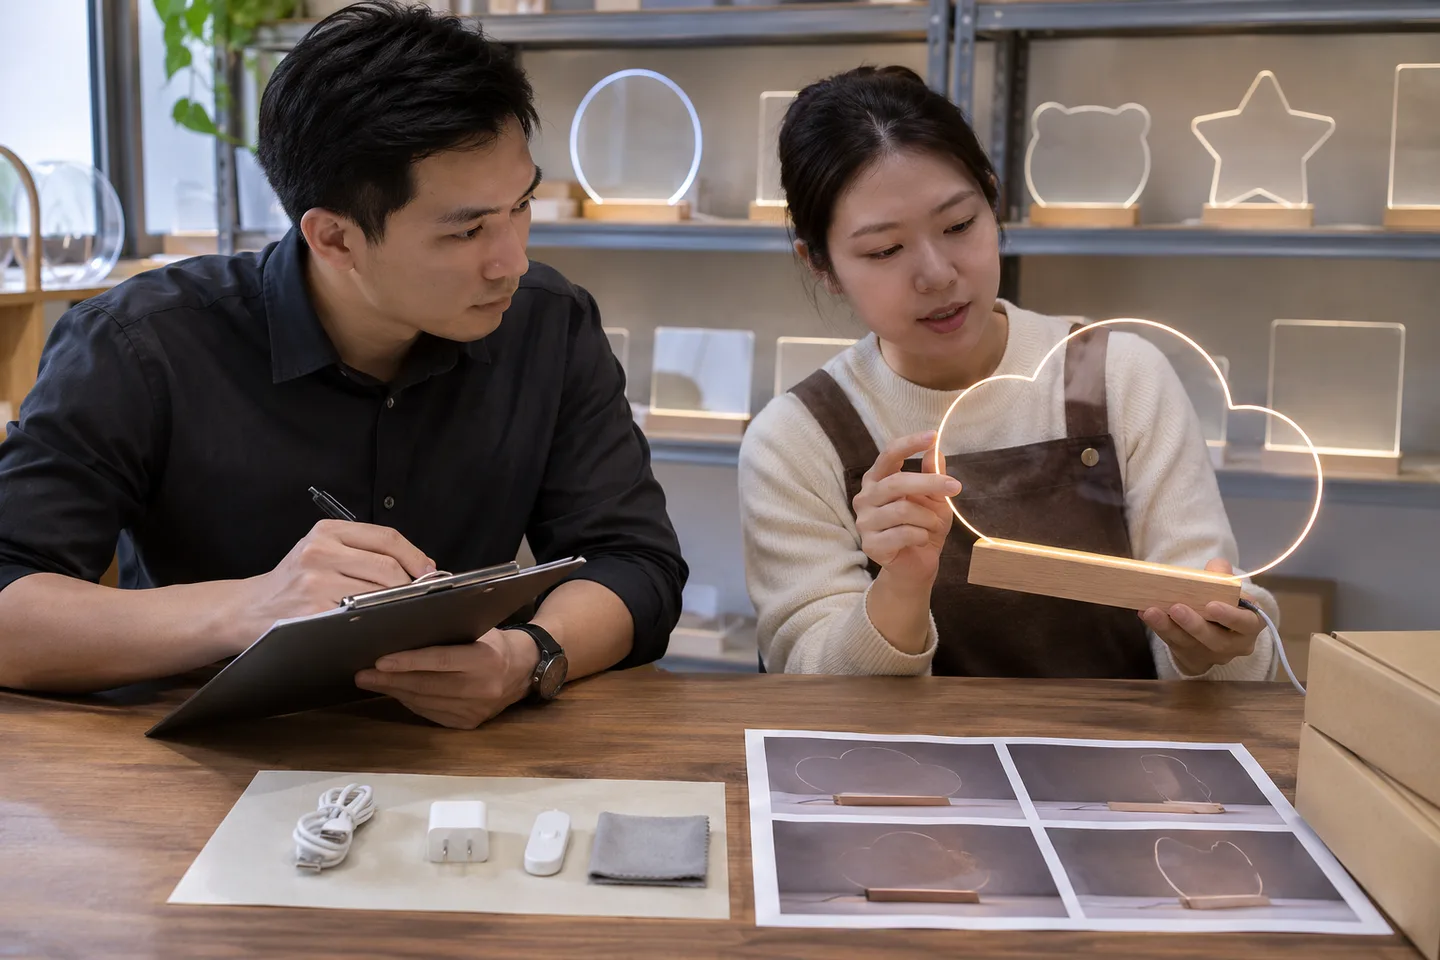
Assign identity, custody and decision status before a sample leaves
Give every loan unit a sample code, configuration record, condition photos, supplied-content list, intended reviewer, dispatch and return dates, handling notes and approval-status label. Check the unit and accessories at every handoff, record observations separately from authorization, and retire samples that no longer represent the current sellable configuration.
1. Start with the buyer sample loan control decision
Give every loan unit a sample code, configuration record, condition photos, supplied-content list, intended reviewer, dispatch and return dates, handling notes and approval-status label. Check the unit and accessories at every handoff, record observations separately from authorization, and retire samples that no longer represent the current sellable configuration.
A useful buying decision begins with the exact product configuration and customer task, not a generic claim about LED boards. For this topic, the controlled subject is the physical LED drawing-board sample, accessories, custody record and review purpose shared with a buyer or channel partner. Record sample code, configuration and contents, condition, custodian and location, review purpose, return or retirement status before comparing samples. Those facts determine whether two units are genuinely comparable and prevent a visible difference from being attributed to the wrong material, component, power source, or process. This record remains specific to the buyer sample loan control decision.
This guide applies buyer sample loan control to one identified LED drawing-board configuration, channel and commercial workflow. It does not guarantee platform acceptance, sales, destination compliance or results outside the recorded scope. The review should therefore separate three questions: what the buyer needs, what the identified sample actually demonstrates, and which conclusion still requires qualified engineering, laboratory, or destination-market review. That separation gives procurement teams a defensible basis for a request for quotation without turning a short sample observation into a lifetime, safety, or compliance promise. This record remains specific to the buyer sample loan control decision.
Before contacting suppliers about buyer sample loan control, assign an owner to the commercial need, an owner to the technical evidence, and a person authorized to accept a trade-off. Give them the same one-page brief and require each comment to reference the sample code or specification field. This simple handover matters when the importer, brand, testing adviser, inspection company, and factory work in different locations. It prevents a merchandising preference from being reported as a regulatory rule and prevents an unresolved technical question from disappearing inside a general approval. Record the final decision, evidence reviewed, open items, and next review trigger in language a future replenishment team can understand. This record remains specific to the buyer sample loan control decision.
- Name the exact model, panel, base, cable, marker set, and operating condition involved.
- Use a sample can support a decision only while its identity, configuration, condition, custody and approval status remain traceable as the commercial decision rule.
- Record unknowns rather than filling them with catalogue assumptions.
2. Understand what can change the result
Handling, cleaning, accessory substitution and product changes can make a familiar sample materially different from the configuration it is assumed to represent.
buyer sample loan control depends on the complete identified configuration
ISO documented-information guidance supports identification, protection, retention and change control, while controlled-sample practices separate observation from authorization. A buyer does not need to reproduce a material-science laboratory to manage this risk, but the quotation and sample plan must identify the variables that the factory controls. Ask which inputs are fixed by drawing or bill of materials, which depend on the production route, and which can vary with environment or operator technique. This record remains specific to the buyer sample loan control decision.
Primary technical references in this guide explain the general mechanism or measurement scope; they do not certify a LumDigi model or create a universal acceptance limit. Use them to ask better questions, then rely on product-specific drawings, supplier declarations, samples, and suitable test evidence. This is especially important when a method developed for sheet material, a connector, a lamp, or an art material is being used only as context for a finished drawing-board assembly. This record remains specific to the buyer sample loan control decision.
- Identify the mechanism and the buyer decision before choosing a test.
- Keep sample code and configuration and contents visible in the evidence record.
- Use external references as context, not as certification of a LumDigi product.

3. Build a sample matrix before testing
Compare controlled configurations that isolate the variables most likely to change the buyer sample loan control result.
Use one approved SKU and one meaningful variant, exception or changed record. Follow both through the buyer sample loan control workflow so the team validates the control rather than reviewing only an ideal example. Give each unit a sample code and retain the configuration record with photographs taken before the review. If a supplier proposes an alternate input, make it a separate matrix row rather than silently replacing the approved reference. This protects the buyer from approving one combination and receiving another. This record remains specific to the buyer sample loan control decision.
Keep the matrix small enough to interpret. Change one significant variable at a time where practical, while holding product revision, supplied contents, approved artwork, identifiers, record owner, destination and release authority constant. Include a repeat unit when the commercial risk is lot consistency rather than a one-off demonstration. A buyer sample is evidence for a defined decision; it is not automatically a statistically representative production result. This record remains specific to the buyer sample loan control decision.
- Use coded samples and retain an untouched reference.
- Change one important variable at a time where practical.
- Record the actual product, setup and environment beside every result.
4. Use a repeatable review method
Use a written, repeatable method that reproduces the buyer's actual decision conditions without turning an in-house review into an unsupported certification claim.
Use a controlled worksheet, named evidence files and a physical comparison. Record the source, owner, revision, destination, review status, exception and approval; reopen affected records after any relevant change. Write the sequence before viewing the result so observers do not change the method after seeing a preferred sample. Record setup, duration, handling, power source, room condition, and any cleaning or reset step that could influence the next observation. This record remains specific to the buyer sample loan control decision.
Capture surface and edge condition, base and cable identity, marker completeness, operation, pack state, custody history. Use neutral photographs and short unedited video where motion or control behavior matters, and label every file with the sample code. Do not enhance glow, hide a defect with exposure, or crop away the cable and base when those elements are part of the question. Installation preparation should use only the proposed accessories and a stable, ordinary application setup. This record remains specific to the buyer sample loan control decision.
- Photograph the starting condition before handling or adjustment.
- Use one defined sequence, observation distance and operating condition.
- Keep files traceable to the sample code and reviewer.
5. Interpret observations without overclaiming
Interpret the recorded evidence against the stated customer requirement and preserve open questions for the appropriate technical, legal or laboratory reviewer.
A sample review can show whether the observed configuration meets the buyer's stated task under recorded conditions. It cannot by itself establish every production unit, every environment, or an unspecified service period. Treat the outcome as evidence for the identified product, data set, sample, pack or order on the recorded date. Do not turn it into a universal legal, safety, platform, commercial or performance claim. If the buyer needs a measured value or regulated conclusion, define the applicable method, specimen, equipment, laboratory competence, and report before assigning a limit. This record remains specific to the buyer sample loan control decision.
Use three result states: accepted for the defined purpose, rejected against a written criterion, or open pending evidence. Avoid labels such as premium, safe, durable, uniform, or compliant unless the claim has a defined meaning and support. Where two configurations both work, preserve the trade-off rather than forcing a winner. The best sourcing choice is the one that meets the customer requirement with controllable production and truthful product communication. This record remains specific to the buyer sample loan control decision.
- Separate preference, functional acceptance and measured evidence.
- State the configuration and limitations beside the result.
- Reopen approval after a relevant material, process or component change.
| Decision field | Record in the buyer file |
|---|---|
| Identity | SKU, revision, set contents and approved reference |
| Evidence | Source, owner, physical check and exception |
| Release | Destination, effective date and authorized decision |
6. Translate the decision into the RFQ
Turn the accepted buyer sample loan control condition into explicit RFQ fields, sample references, evidence requests and change-notification rules.
The RFQ should identify sample purpose, required configuration, recipient and destination, loan period, return method, decision and retention status. Attach the sample matrix, approved photographs, and any drawing or artwork revision needed to make those fields unambiguous. Ask the supplier to mark confirmed, conditional, optional, and unsupported points. This produces comparable quotations and prevents an attractive reference image from becoming an unintended specification. This record remains specific to the buyer sample loan control decision.
Request the proposed evidence with the quote: material or component identity, current datasheet where relevant, sample lead time, change-notification route, and the inspection checkpoint that will confirm production. Use LumDigi's custom design process for shape and presentation discussions, review a relevant shaped LED board reference, and send the controlled brief through the B2B enquiry page. Availability and final specifications must be confirmed for the selected model. This record remains specific to the buyer sample loan control decision.
- Require a response against every named field.
- Attach approved sample photographs and document revisions.
- Mark confirmed, conditional, excluded and unresolved items separately.
7. Carry the approved condition into production
Hold the approved inputs and process conditions through incoming review, assembly and in-process verification, then document any authorized deviation.
Production control should cover sample register, dispatch condition photos, contents checklist, custody receipt, return inspection, retirement record. Link each checkpoint to a drawing, bill-of-material line, approved sample, work instruction, or recorded setting rather than relying on memory. If a change affects the mechanism discussed in this guide, pause and evaluate it against the approved decision before allowing the new condition into the order. This record remains specific to the buyer sample loan control decision.
Factory testing should answer the commercial question with a repeatable method and traceable units. It should not be described as third-party certification unless it genuinely is. Retain representative evidence from start-up, in-process review, and the production lot where the risk justifies it. For a custom shape or private-label set, synchronize the panel, base, marker, cable, insert, and pack revisions so a correct component is not assembled into the wrong configuration. Compare the evidence plan with this related buyer guide before final approval. This record remains specific to the buyer sample loan control decision.
- Link checkpoints to the bill of materials, drawing or work instruction.
- Retain start-up and in-process evidence from identified units.
- Route changes through written buyer approval when they affect the decision.
8. Verify the shipment-level evidence
Verify the agreed buyer sample loan control evidence on identified finished units and connect findings to an authorized release, correction, reinspection or hold decision.
Shipment inspection can check sample code is visible, configuration is current, contents are complete, condition is recorded, approval status is not overstated, using the buyer's approved references and sampling instruction. The report should identify the lot, selected units, method, actual observations, photographs, limitations, and disposition. A pre-shipment check is valuable commercial evidence, but it does not replace material qualification, laboratory testing, or regulatory assessment required for the destination market. This record remains specific to the buyer sample loan control decision.
When a finding occurs, describe it against the requirement and separate observation from cause. Define correction, reinspection, concession, or hold authority before shipment release. Archive the report with the purchase order, change notices, and approved sample. This creates a practical trace from customer requirements to production and reduces disputes built on unlabeled photos or recollection. This record remains specific to the buyer sample loan control decision.
- Record the lot, variant, selected unit and method.
- Describe observations against the written requirement.
- Archive findings, corrections and final disposition together.
9. Conclusion: make buyer sample loan control a controlled buying decision
Control buyer sample loan control through a defined requirement, identified samples, repeatable evidence, production checkpoints and truthful claim boundaries.
Effective buyer sample loan control keeps the physical product, commercial record and channel execution aligned without hiding unresolved decisions. The process is intentionally narrower than a broad product claim: define the need, compare identified configurations, record the method, and translate the decision into production and inspection controls. That sequence gives retail, distribution, and private-label teams information they can explain accurately to colleagues and customers. A supporting procurement guide can be used to align the adjacent buying decision without collapsing two specifications into one. This record remains specific to the buyer sample loan control decision.
For LumDigi, send the target market, channel, preferred board shape, power arrangement, marker set, quantity scenario, packaging direction, and the specific buyer sample loan control question. LumDigi can confirm facts for offered configurations and organize a relevant sample discussion. Buyers remain responsible for destination-market decisions and should use qualified reviewers where standards, safety, legal, or laboratory conclusions are required. This record remains specific to the buyer sample loan control decision.
- Approve a complete configuration rather than an isolated photograph.
- Keep product, artwork, instructions and inspection evidence aligned.
- Reconfirm the decision after relevant changes.
Frequently asked questions
What should a buyer specify about buyer sample loan control?
Specify sample purpose, required configuration, recipient and destination, loan period, return method, decision and retention status. Attach the identified sample and state which fields are requirements, preferences, or open questions.
Can one sample prove every buyer sample loan control result?
No. A sample can support the defined decision under recorded conditions. Treat the outcome as evidence for the identified product, data set, sample, pack or order on the recorded date. Do not turn it into a universal legal, safety, platform, commercial or performance claim. Production consistency, lifetime, safety, and regulatory conclusions need evidence appropriate to those separate claims.
Which changes should trigger a new review?
Review changes to sample register, dispatch condition photos, contents checklist, custody receipt, return inspection, retirement record. The buyer and supplier should agree which changes require notification, a comparison sample, updated documents, or qualified assessment.
What belongs in shipment inspection?
The plan can verify sample code is visible, configuration is current, contents are complete, condition is recorded, approval status is not overstated against approved references. It should identify the lot, method, selected units, findings, limitations, and authorized disposition.
Image planning for this topic
These notes document the role and intended context of the two visuals used in this guide.
Show a controlled buyer review of buyer sample loan control
- Placement
- hero
- Caption
- Illustrative AI-generated photograph: an Asian buyer and Chinese engineer compare identified buyer sample loan control samples under controlled conditions.
- ALT text
- Asian buyer reviewing buyer sample loan control samples for LED drawing boards
View AI image direction
Use case: photorealistic-natural. Asset type: editorial photograph for a LumDigi B2B LED acrylic drawing board technical guide. An Asian overseas buyer and Chinese sample coordinator review a coded shaped LED drawing board, accessory checklist and neutral condition photographs. Landscape 3:2 composition, candid documentary commercial photography, natural modest lighting, realistic transparent acrylic, restrained plausible LED glow, genuine workshop or sample-room texture, believable anatomy. If employees appear, every employee is a Chinese/Asian adult. No invented logos, certification marks, readable documents, readable instrument values, numerical test results, watermark, or text overlay. This is an illustrative planning scene, not proof of an actual LumDigi test, factory result, shipment, or customer project.
Show factory verification of buyer sample loan control
- Placement
- after-second-section
- Caption
- Illustrative AI-generated photograph: Chinese technicians record production evidence for the approved buyer sample loan control condition.
- ALT text
- Chinese technicians checking buyer sample loan control during LED board production
View AI image direction
Use case: photorealistic-natural. Asset type: editorial photograph for a LumDigi B2B LED acrylic drawing board technical guide. Chinese sample-room staff inspect returned LED drawing-board samples, bases, cables and markers before updating a custody register. Landscape 3:2 composition, candid documentary commercial photography, natural modest lighting, realistic transparent acrylic, restrained plausible LED glow, genuine workshop or sample-room texture, believable anatomy. If employees appear, every employee is a Chinese/Asian adult. No invented logos, certification marks, readable documents, readable instrument values, numerical test results, watermark, or text overlay. This is an illustrative planning scene, not proof of an actual LumDigi test, factory result, shipment, or customer project.
Turn the article into a practical sourcing brief
Use the checkpoints above to document the product, evidence, packaging, and approval decisions relevant to your market. A clear brief helps suppliers respond to the same commercial question and gives your team a traceable basis for the next step.
Useful external references
- ISO 10013:2021 documented information guidance
Official ISO page on developing and maintaining documented information needed for effective quality-management processes.
- ISO/IAF Auditing Practices Group: processes
Official ISO/IAF guidance on process inputs, outputs, criteria, responsibilities, evidence and controlled change.
- GS1 Global Data Model Attribute Implementation Guideline
Official GS1 guidance for harmonized trade-item master data and linked packaging hierarchy information.
How to Approve a LED Drawing Board Sample Before Bulk Production
A practical B2B guide for buyers approving a production-ready custom or wholesale set who need to turn a loose sample into a controlled product, packaging, and release decision before bulk production is authorized.
Read article
LED Drawing Board Supplier Sample Tracking Guide
A practical B2B guide for importers, distributors and private-label teams who need to make a controlled sourcing decision using the approved board, pack, sample and evidence.
Read article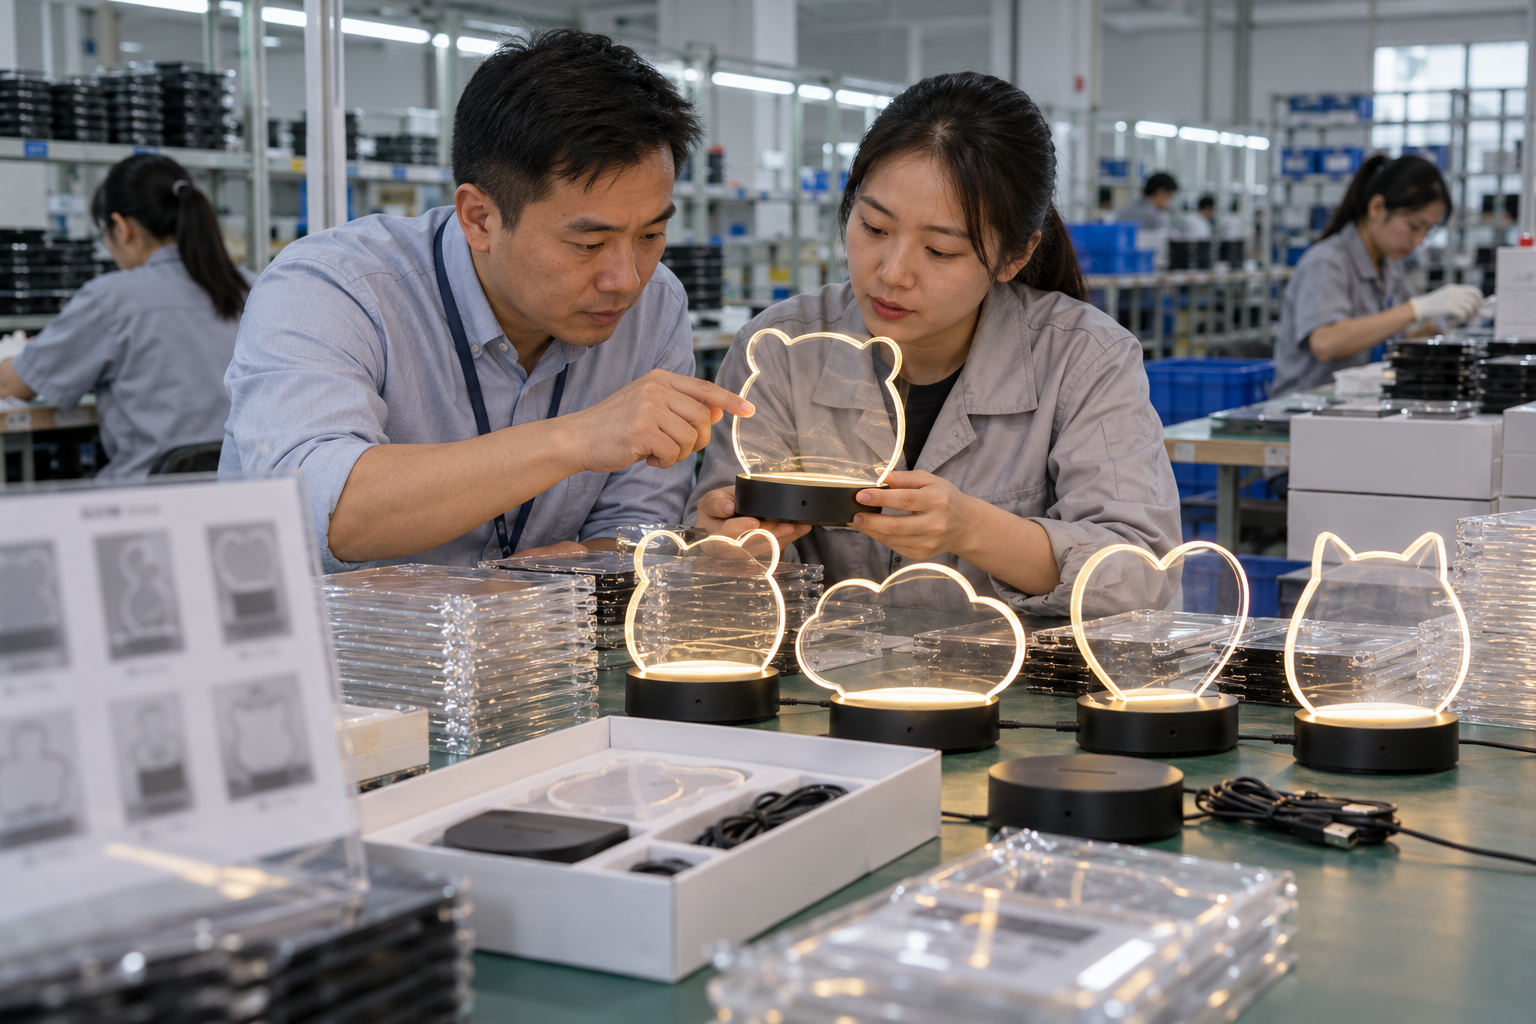
Golden Sample Control for LED Drawing Board Production
A procurement guide to reference-sample identity, approval scope, storage, access, inspection use, replacement and change control for private-label LED board orders.
Read article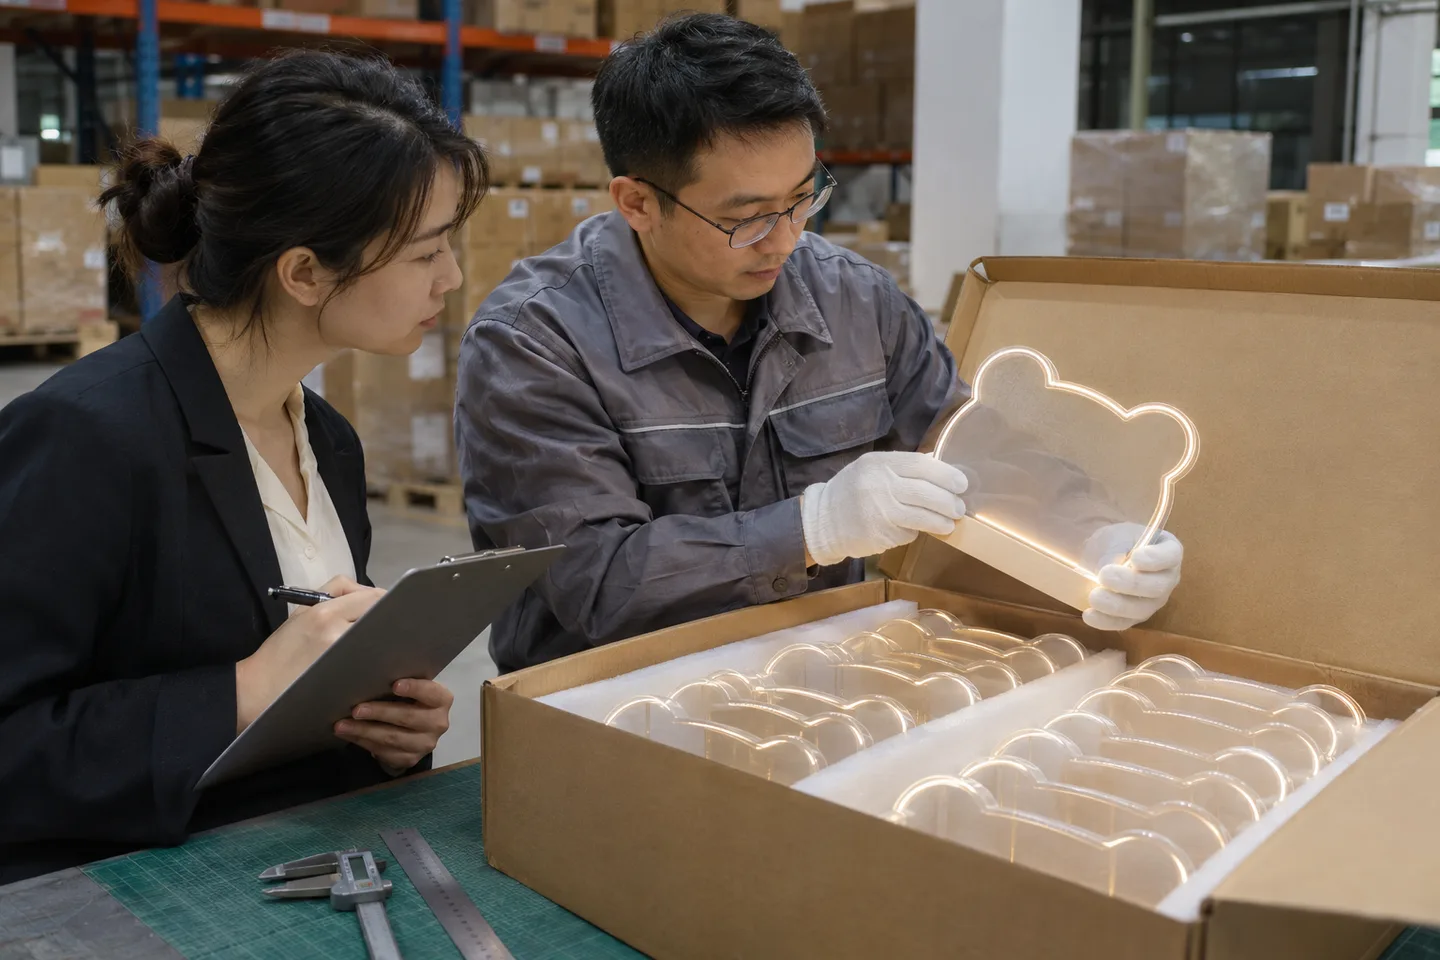
Case-Pack Validation for LED Drawing Board Buyers
A buyer guide to confirming the actual shipping case instead of treating quotation dimensions or an early packing concept as final logistics data.
Read article