Product Liability Insurance Questions for LED Drawing Board Importers and Distributors
The direct answer is to ask a licensed insurance broker to assess the buyer's own product, markets, contracts, and coverage needs, while reviewing supplier evidence within its stated scope, while avoiding assuming that a supplier's insurance certificate covers the importer's own liability, every LED board model, every territory, or a product recall expense.
1. Separate product liability, cargo loss, and recall costs
Product liability insurance addresses a different risk from cargo insurance, product-quality remedies, or recall-expense cover; buyers should ask a broker to distinguish each exposure.
A shipment damaged in transit may be a cargo claim. A customer alleging injury or property damage may create a product-liability question. A withdrawal, correction, or recall can create response costs that may not be covered by a standard liability policy. These are different events with different policy language, triggers, exclusions, and parties. An importer should describe its product program, brand role, sales countries, channels, and contracts to a licensed broker rather than assuming one policy or supplier certificate covers everything.
The SBA identifies product liability insurance as a type of coverage for businesses that manufacture, wholesale, distribute, and retail products, and describes it generally as protection against financial loss from a defective product causing injury or bodily harm. That high-level description is not a promise of coverage for a particular claim. The actual insuring agreement, definitions, limits, exclusions, defense costs, territory, and endorsements control. Ask the broker what products and operations are covered and what falls outside the policy.
Keep a separate risk register for cargo, product liability, business interruption, and recall expenses so a gap is not hidden under a broad 'insured' label.
The SBA and insurance regulator resources describe policy categories at a high level. They do not guarantee that any named policy will cover a particular injury, damage, or recall cost.
- Name the loss scenario before asking about a policy.
- Review product liability separately from cargo and recall costs.
- Use a licensed broker for policy interpretation.
2. Start with the importer's own brand and sales exposure
The importer should assess its own coverage needs based on its legal role, markets, products, contracts, sales volume, and customer requirements—not rely solely on a factory's policy.
A private-label importer may be named on product packaging and may sell through retailers, distributors, or ecommerce marketplaces. Each role can affect contractual requirements and risk allocation. Provide the broker with the product category, intended age group as determined by the responsible business, power configuration, markets, estimated annual sales, distribution chain, and key retailer contracts. Do not assume that a supplier policy names the importer as an insured or covers the importer's own defense. Ask how additional insured status, primary and noncontributory terms, notice, and other requested provisions work under the actual policy and law.
A buyer's review should include limit adequacy, per-occurrence and aggregate structures, deductible or retention, products-completed operations, territory, jurisdiction, and relevant exclusions. Ask what happens when a claim alleges a design issue, manufacturing defect, labeling issue, or misuse. Coverage decisions depend on facts and policy wording; a general blog cannot determine the adequacy of a limit. If the retailer contract requires a specific amount or endorsement, have the broker review the wording and feasibility before signing or placing an order.
Maintain an annual renewal calendar and update the broker when the product range, sales territory, or private-label arrangement changes.
A certificate holder is not automatically an insured. Ask counsel and the broker to confirm whether the requested additional-insured status is actually granted by an endorsement.
- Describe buyer role, brands, channels, and destination markets.
- Match customer contract requirements to actual policy wording.
- Reassess after product or territory changes.
3. Read a supplier insurance certificate as limited evidence
A certificate can summarize specified insurance information at a point in time; it is not necessarily the policy, an endorsement, proof of every coverage term, or a guarantee of claim payment.
When a buyer requests a supplier certificate, identify why it is needed, whose contract requires it, and what entity or products it should describe. Check the named insured, insurer, policy period, coverage type, stated limits, territory if shown, and whether a required additional-insured endorsement is attached. A certificate may contain disclaimers and may not amend the policy. Ask the supplier or its broker for a copy of the relevant endorsement if the contract calls for one and if it can be shared. Confirm that the legal entity on the purchase order is the same one shown on the record.
A supplier certificate does not automatically protect the buyer. It may not cover the buyer's own acts, private-label design, local marketing, product modifications, or claims in a given jurisdiction. The buyer's broker and counsel should review both the certificate and the underlying agreement. Avoid promising retailers that a supplier's policy will respond to their claim. Record the document's issue date and renewal reminder, and request updated evidence when the policy period expires or contract requirements change.
Do not infer coverage from a logo or a stated limit alone; the terms and insured relationships matter.
Keep the legal business name consistent across purchase orders, contracts, invoices, and insurance forms. A brand name may not identify the entity that owns the policy.
- Match the insured legal name to the contracting party.
- Review the policy and endorsements, not just a summary page.
- Do not describe supplier insurance as buyer coverage without confirmation.
4. Ask separately about product recall and withdrawal expenses
Liability coverage and product-recall expense coverage may respond to different events; the buyer should ask a broker whether recall, contamination, correction, replacement, or customer notification costs are addressed.
A recall can involve locating inventory, communicating with channels, shipping replacement units, reworking or destroying products, and handling consumer contacts. Those costs are not the same as bodily injury or property damage alleged in a liability claim. Some policies may offer specialized recall coverage or endorsements; terms vary. Ask the broker what event triggers the cover, whether the issue must be accidental or discovered after sale, what expenses are included, what waiting period or retention applies, and whether voluntary withdrawal is treated differently from a regulator-required action.
Also ask how notice and consent conditions work. A business should understand whether it must obtain insurer approval before announcing a recall or incurring costs, while still meeting urgent legal and safety duties. Coordinate the policy review with the company's product-safety response plan and counsel. Do not delay a legally required protective action solely because coverage is uncertain; the responsible business should follow legal advice and the policy's notice process concurrently.
No policy discussion should be written as evidence that a specific product is defective or likely to be recalled.
If a retailer changes its required limit, ask the broker whether the policy can meet that requirement and what premium, terms, or exclusions would change.
- Ask whether recall-specific costs are included or excluded.
- Understand notice, consent, and timing conditions.
- Keep insurance and legal response owners connected.
5. Provide the broker a precise LED board product description
Insurance review is more useful when the broker knows the actual board construction, electrical and battery options, accessories, intended audience, packaging, and markets.
Prepare a controlled product sheet: shape and SKU, acrylic panel and base, lighting components, USB or battery configuration, included markers, intended use, packaging, branding role, sales destinations, and known manufacturing or testing records. Flag any special features or markets the broker should assess. If the product range includes different power designs, describe each separately. The point is not to make a legal product-safety claim; it is to let the broker evaluate the actual operations and exposures rather than a marketing category alone.
Keep the description aligned with the approved sample and production specification. If the board, battery, marker, or packaging changes, update the broker when the change may affect underwriting or policy conditions. The factory can provide product and shipment facts it controls, such as an agreed inspection report or configuration list. It cannot determine an insurer's coverage or substitute for independent product-risk review. Avoid sending confidential customer information beyond what the broker needs and protect technical data under the applicable agreements.
Use the same product name and revision in contracts, invoices, technical files, and insurance correspondence where possible.
Coverage can vary by territory and jurisdiction. The buyer should tell the broker where goods are sold and where claims could be brought.
- Build one broker-ready description per materially different configuration.
- Distinguish facts, claims, and unresolved risk questions.
- Update the file when design or markets change.
6. Align insurance requirements with supplier contracts
Insurance clauses, indemnities, warranties, and quality responsibilities should be reviewed together because one clause does not replace or guarantee the coverage described in another.
Retailer and distributor agreements may require certificates, limits, additional insured status, notice of cancellation, or particular territory. Supplier contracts may allocate defect response, indemnity, document provision, and cooperation duties. Ask counsel to confirm that the obligations are clear, mutual where appropriate, commercially achievable, and consistent with the actual policy. Insurance may not cover contractual liability assumed beyond what the policy allows. A certificate that shows a limit does not prove that every indemnity obligation is insured.
Keep executed contracts and endorsements together. Create a matrix of requirement, responsible party, evidence, due date, and reviewer. If a term cannot be met, resolve it before the product launches rather than representing compliance that has not been confirmed. In cross-border supply chains, entity names, governing law, jurisdiction, and enforceability can be important; obtain jurisdiction-specific legal advice. The buyer should not expect a Chinese supplier to provide the importer's own coverage or assume the importer can transfer all product risk contractually.
A realistic allocation supports coordination, but the buyer still needs its own risk management and policy review.
Product recall coverage may have narrow triggers and defined expense categories. Ask for examples from the policy wording rather than relying on the coverage label.
- Cross-check contract obligations with policy language.
- Record endorsements and renewal dates.
- Resolve insurance gaps with broker and counsel before launch.
7. Keep a renewal and evidence process
Insurance evidence should be refreshed when policies renew, product lines or markets change, retailer requirements change, or an incident reveals a new exposure.
Assign a policy owner and renewal calendar with enough time to request updated terms, endorsements, and certificates. Check that the insured entity names remain correct after a corporate change. Update product descriptions and sales estimates; inform the broker when a new shape, battery variant, retail channel, or country is added if it could affect underwriting. Keep a record of the broker's advice and the questions answered, while treating the actual policy as controlling. Do not rely on an old certificate after its stated policy period.
A tabletop review can connect claims intake, CPSC escalation, insurer notice, and customer communications. It should clarify who contacts the broker and counsel, which records are preserved, and what approvals are required before public statements. A drill does not guarantee coverage or a claim outcome; it helps the team understand its process. The buyer can link this to its existing recall-readiness plan and cargo-claim workflow while maintaining separate triggers for each type of loss.
Store sensitive policies with access controls and a simple index so designated staff can find the correct form quickly.
Do not assume the same supplier policy applies to affiliates or subcontractors unless the named insured and policy provisions support that conclusion.
- Review policy dates, entities, territories, and endorsements.
- Update the broker after material product or channel changes.
- Connect claim response to the recall and incident process.
8. Conclusion: ask the right insurance question for each risk
Importers should use their own broker to evaluate product-liability and recall exposure, and should treat a supplier certificate as limited evidence with a defined entity, period, and scope.
Product liability, cargo loss, and product-recall expenses are separate questions. The buyer's policy and contract should reflect its role, branded products, sales geography, and customer requirements. The SBA and state insurance guidance provide useful general descriptions, but only a licensed broker and counsel can interpret a policy for a particular importer. Accurate product identity, current documents, and clear responsibilities support a more useful review than assuming that a supplier's coverage solves every downstream exposure.
For a LumDigi project, provide the board configuration, destination markets, brand role, and specific certificate or contract requirement. LumDigi can confirm supplier-held product details and discuss available documents. Your broker and legal adviser should decide coverage needs, wording, and contract allocation.
A review of insurance is commercial risk management, not evidence of product compliance, quality, or a product defect.
- Ask about buyer coverage and supplier evidence separately.
- Review current policy wording and any endorsements.
- Do not make coverage promises without broker confirmation.
Frequently asked questions
Does a supplier's insurance certificate cover my importing company?
Not automatically. The certificate may identify the supplier's insurance at a point in time, but the buyer should review the underlying policy and endorsements with its own broker and counsel to determine insured status and scope.
Is product liability insurance the same as cargo insurance?
No. Product liability addresses a different type of alleged loss from cargo transit damage. Policy terms and claim triggers differ, so buyers should evaluate each risk separately.
Does general liability always cover a product recall?
Do not assume so. Ask a licensed broker whether recall, withdrawal, correction, replacement, and notification expenses are included, excluded, or available through separate coverage.
What product details should an LED board importer give its broker?
Describe the exact SKU and revision, shape, materials, power or battery option, accessories, branding role, intended markets, channels, estimated sales, and retailer contract requirements. The broker may request more detail.
Image planning for this topic
These notes document the role and intended context of the two visuals used in this guide.
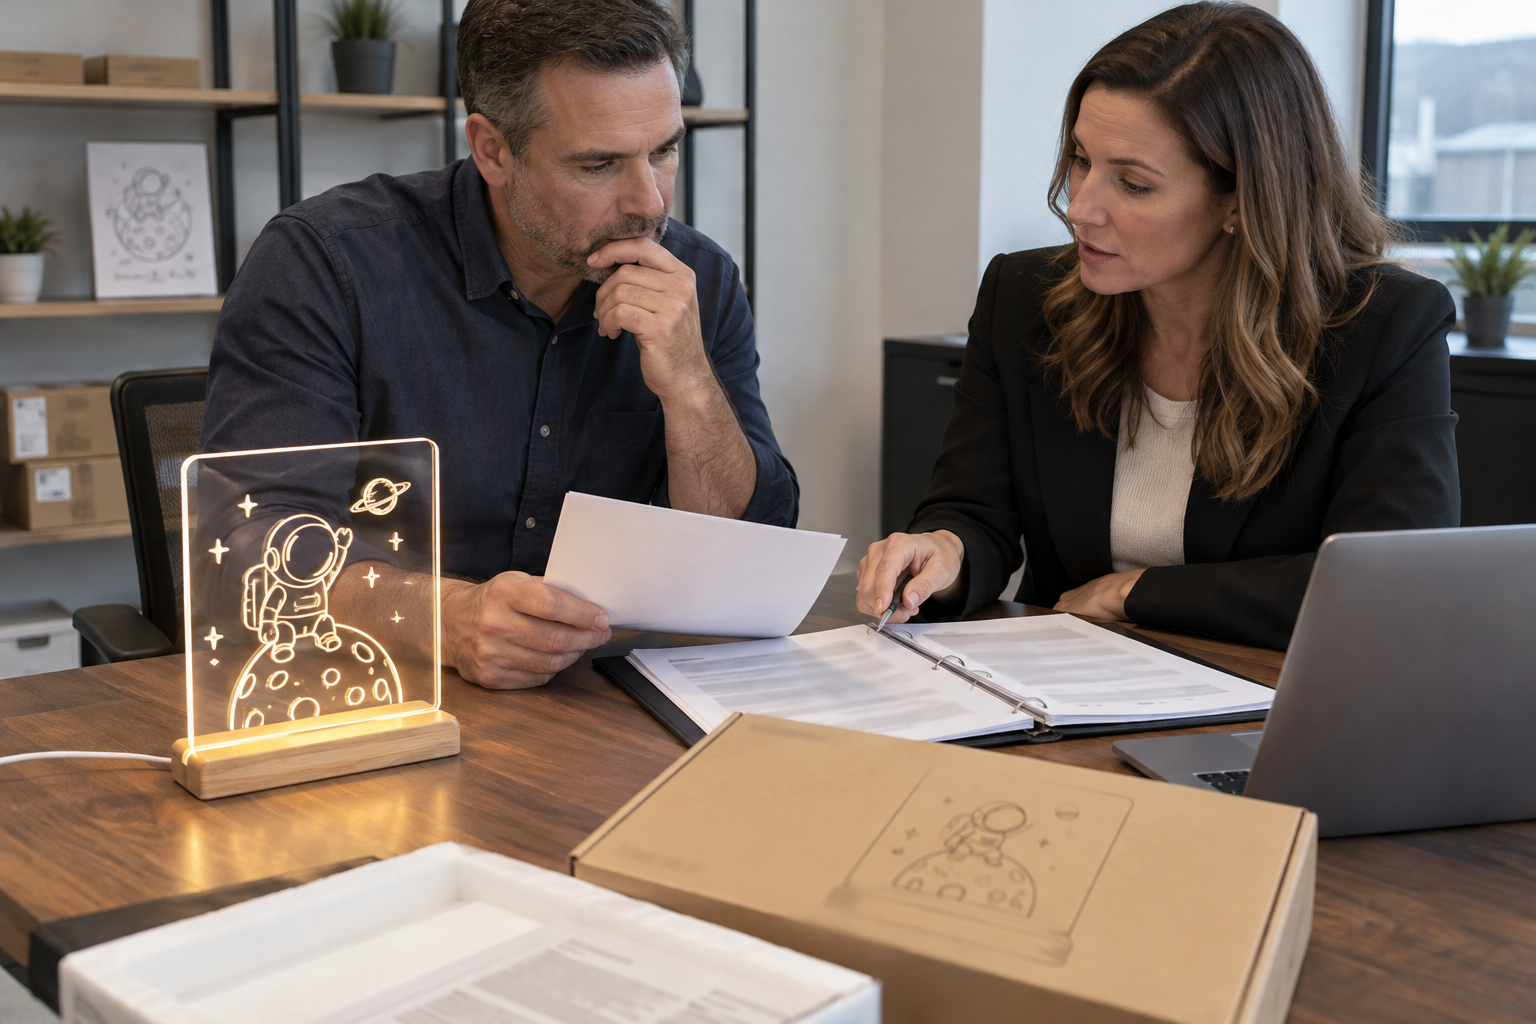
Show a buyer decision context for Product Liability Insurance Questions for LED Drawing Board Importers and Distributors.
- Placement
- hero
- Caption
- A buyer and insurance adviser review contract and coverage questions for a consumer product program.
- ALT text
- LED drawing board product liability insurance B2B buyer review
View AI image direction
Photorealistic documentary photograph for a LumDigi B2B article about Product Liability Insurance Questions for LED Drawing Board Importers and Distributors. Photorealistic documentary photograph of a U.S. importer and licensed insurance adviser discussing a consumer-product risk file with a shaped acrylic LED drawing board sample on the table, generic blank policy pages with all writing blurred, neutral professional office, no insurer branding, no certificate, no readable text, no watermark, landscape. Real acrylic texture, candid commercial setting, landscape composition, no readable logos, no certificates, no text overlay, no watermark.
Show practical factory or shipment-review context for Product Liability Insurance Questions for LED Drawing Board Importers and Distributors.
- Placement
- after-key-considerations
- Caption
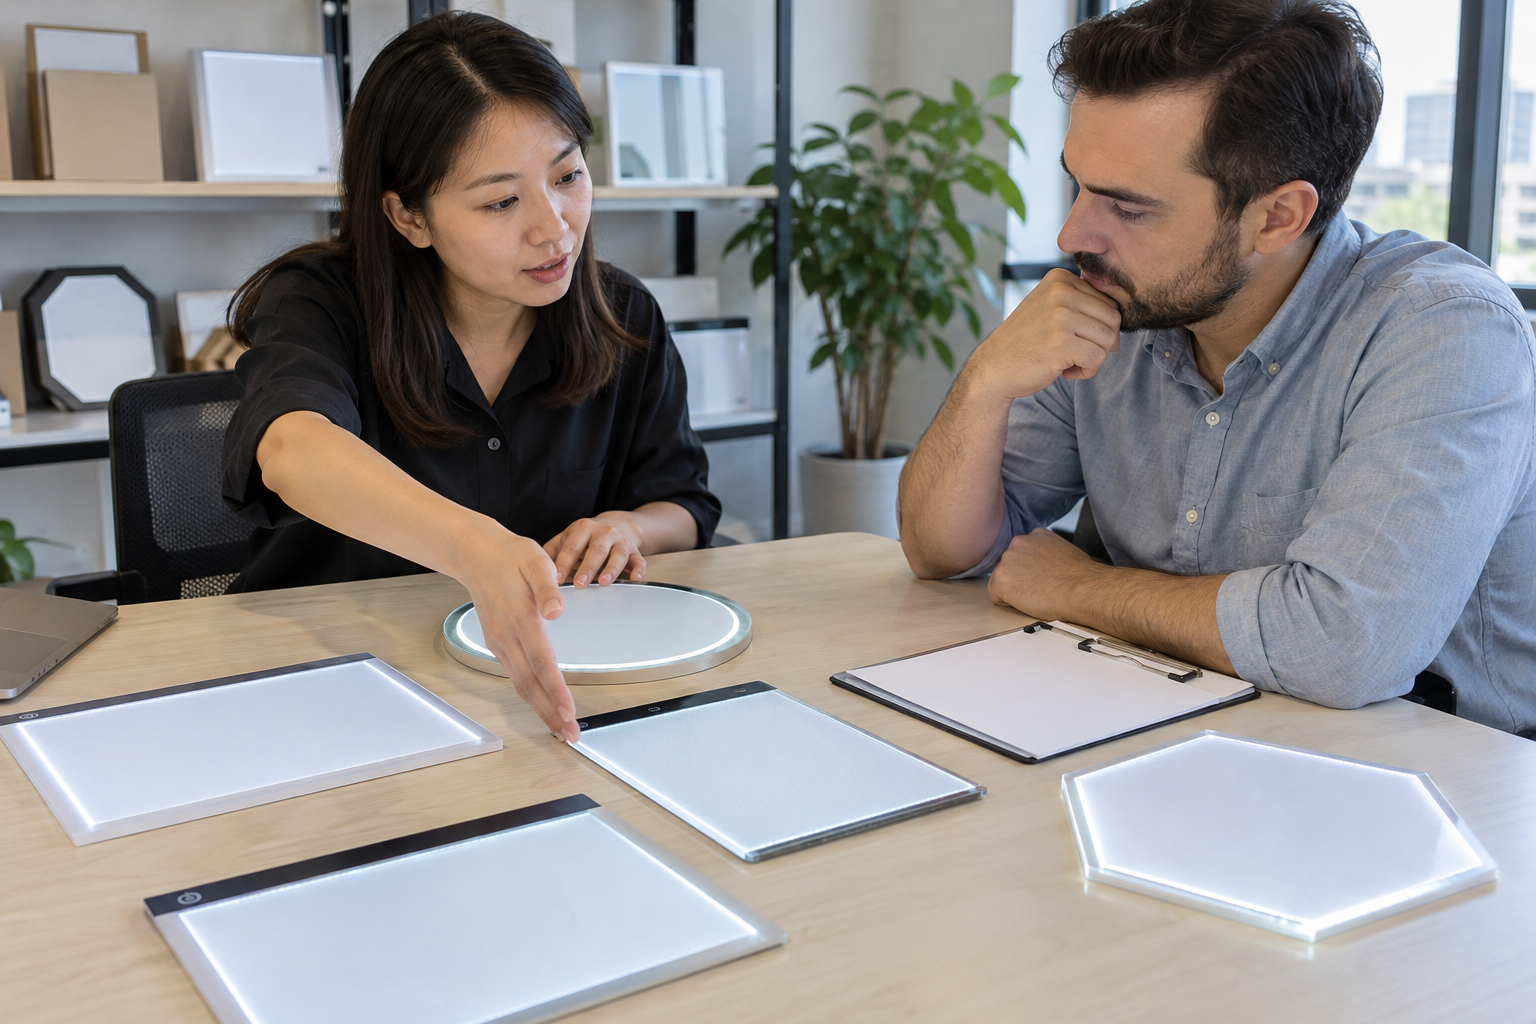
- A sourcing team identifies the LED board range and business entities before requesting insurance evidence.
- ALT text
- LED drawing board product liability insurance Chinese factory review
View AI image direction
Photorealistic documentary photograph for a LumDigi B2B article about Product Liability Insurance Questions for LED Drawing Board Importers and Distributors. Photorealistic business documentary scene of a Chinese Asian supplier coordinator and overseas distributor identifying different LED drawing board shapes, buyer brand labels removed, on a clean meeting table beside a blank insurance-information request, no readable names, no certificates, no logos, natural light, landscape. Real acrylic texture, candid commercial setting, landscape composition, no readable logos, no certificates, no text overlay, no watermark.
Turn the article into a practical sourcing brief
Use the checkpoints above to document the product, evidence, packaging, and approval decisions relevant to your market. A clear brief helps suppliers respond to the same commercial question and gives your team a traceable basis for the next step.
Useful external references
- U.S. Small Business Administration: Business insurance overview
SBA describes product liability insurance as coverage for businesses that manufacture, wholesale, distribute, or retail products, while recommending businesses assess their own risks and compare terms.
- California Department of Insurance: Commercial insurance guide
State regulator overview of commercial general liability coverage sections, including products liability and completed operations; actual coverage depends on policy language and state law.
- GS1 Product Image Standard
Primary guidance for consistent product-image identification and digital assets.
Cargo Insurance and Damage Claim Evidence for LED Drawing Boards
A B2B buying guide for importers, freight coordinators, and distribution operations teams who need to confirm cargo cover and evidence responsibilities before dispatch, then preserve condition records if a loss occurs.
Read article
Recall Readiness and Lot Traceability for LED Drawing Board Importers
A practical importer workflow for complaint intake, product and lot identification, distribution records, and timely escalation of potential consumer-product concerns.
Read article
LED Drawing Board Supplier Evaluation Checklist for B2B Buyers
A practical B2B guide for importers, retailers, and private-label buying teams who need to compare potential suppliers through documented capability, communication, samples, quality controls, and commercial scope rather than a catalogue image alone.
Read article
LED Drawing Board Distributor Onboarding Kit Guide
A B2B buying guide for manufacturers, distributors, and regional sales teams who need to build an onboarding kit from current product facts, approved assets, defined exclusions, and named support contacts.
Read article